


 (916) 313-3030
September 18th, 2026
Can a Trustee Pay Himself From a Family Business Owned by the Trust?
Publication Date September 18, 2026 in Trustee’s Duty
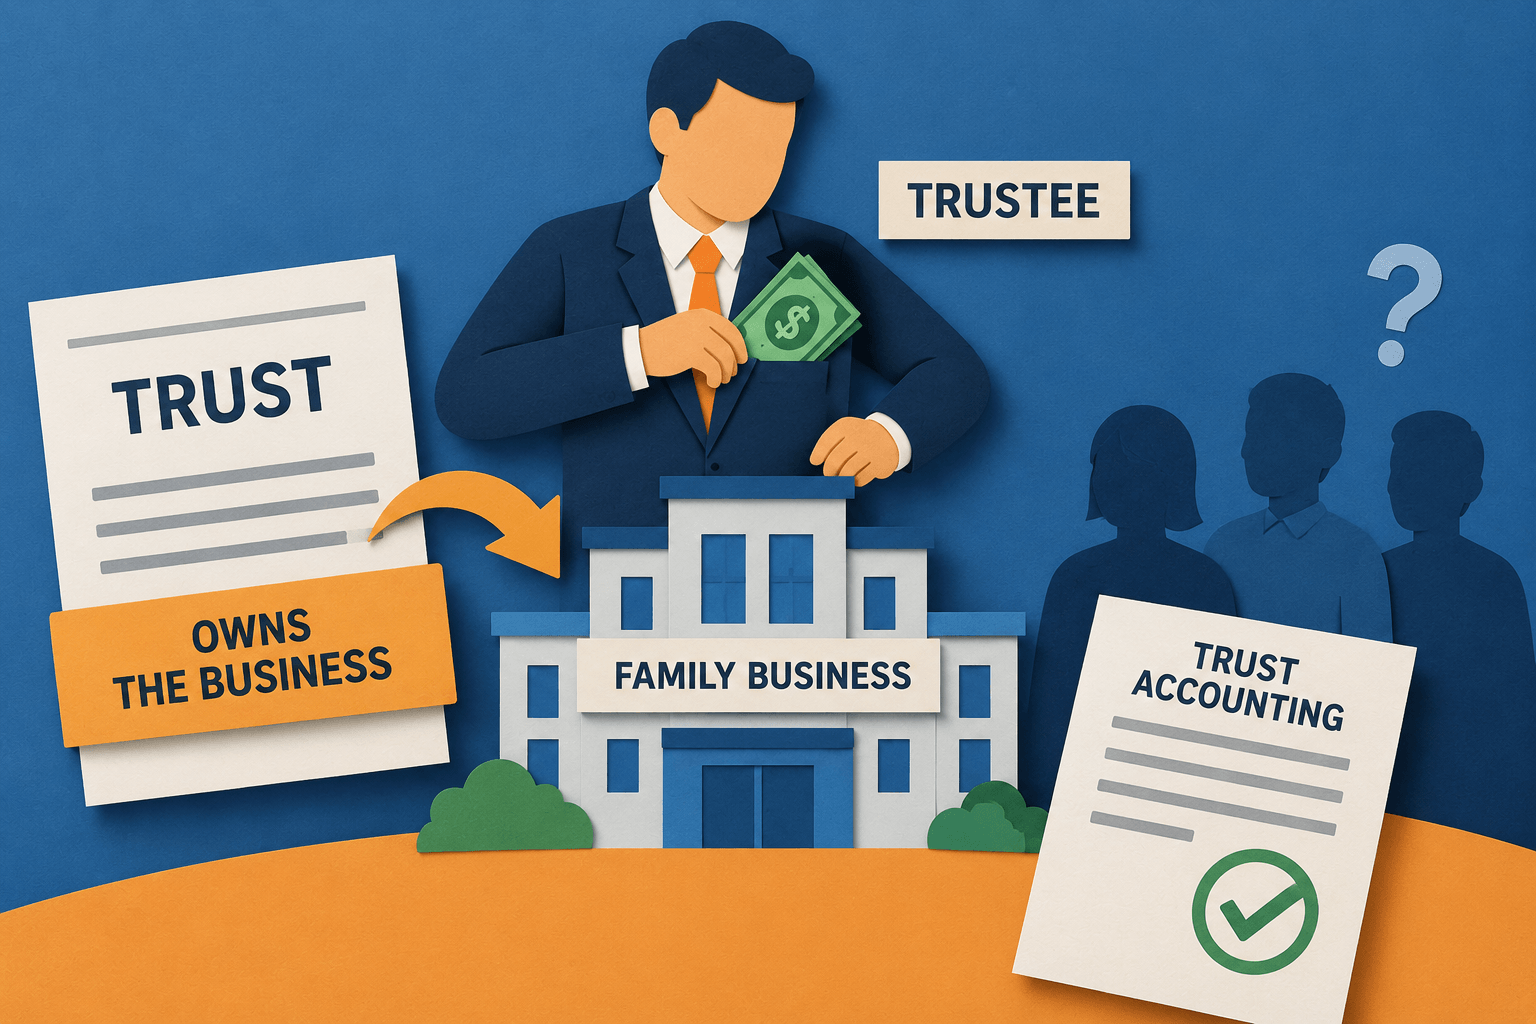
Yes, within limits — and the limits are narrower than most trustees behave as though they are. A trustee who manages a company the trust owns may receive reasonable compensation for that work. What he may not do is set his own salary, bonus, lease, and management fee without scrutiny, and then report none of it to the beneficiaries. Under California law, that money still belongs to the trust. It has simply left at a level the trust accounting does not reach.
That last sentence is the whole problem, and it is why these cases go undetected for years.
General information about California law, not legal advice. Attorney advertising under CRPC 7.1.
The one thing beneficiaries are never told
When a trust owns an operating company, the money leaves at the company level, not the trust level — so a perfectly clean trust accounting is entirely consistent with millions of dollars being taken.
A trust accounting reports the trust’s receipts and the trust’s disbursements. If the trust’s only asset is stock in a corporation or a membership interest in an LLC, the accounting reports what the company sent to the trust. It does not report what the company paid to anyone else along the way.
So a beneficiary can receive six consecutive annual accountings, each prepared by a competent accountant and balancing to the dollar, while the value of his inheritance is drawn down every month by a person the accounting never names in that capacity.
Nothing is hidden. Nothing has to be. The information simply lives in a different set of books.
What that looks like
A father builds a company over forty years. He dies. His trust owns it.
One son has run the business since before the father got sick, and keeps running it. The other children live elsewhere. Every spring they receive an accounting from the trust. It reports a modest distribution from the company, some interest, and property tax on a parcel the trust holds. It balances. It has balanced every year for six years.
What it does not report, because these are not the trust’s disbursements, is the son’s salary. Or the bonus, calculated against a performance threshold he set. Or the lease of the company’s warehouse from a limited liability company he owns personally. Or the management fee paid to a consulting entity with no employees and one member.
Six years of clean accountings.
The children were not asking the wrong questions. They were asking them of the wrong document.
Six ways value leaves a trust-owned company
Executive compensation. Salary and bonus set by the person receiving them. Reasonable pay for real work is legitimate. Compensation untethered from market rate, from company performance, or from any independent approval is not.
Related-party transactions. The company leases premises from an entity the trustee owns. It buys from a supplier he controls. It sells to one on favorable terms. Each transaction is arm’s length only in form.
Management and consulting fees. A separate entity, often with no employees, invoices the operating company for services that are difficult to describe and impossible to benchmark.
Retained earnings. Profits are simply never distributed to the trust. The trustee draws a salary; the beneficiaries wait. The company grows in book value while producing nothing the beneficiaries can use, and the trustee controls when that ever changes.
Phantom and synthetic equity. Deferred compensation plans that pay out on a valuation event, measured against thresholds the trustee participates in setting. These can transfer enormous value without a single share changing hands.
Entity-level entrenchment. This is the most sophisticated and the most damaging. The operating agreement names the trustee as manager in his individual capacity rather than in his capacity as trustee. Fiduciary duties are waived or narrowed to the maximum the governing law permits. Removal requires a supermajority he controls. Remove him as trustee, and he still runs the company — because his authority never came from the trust in the first place.
What California law actually requires
A trustee must manage the trust only in the beneficiaries’ best interests (Prob. Code § 16002) and treat them equally (§ 16003). Transactions between a trustee and the trust in his own interest are presumed to be voidable, and he may not use his position to profit beyond what the law or the instrument permits (§ 16004). His compensation as trustee must be reasonable when the instrument is silent (§ 15681).
None of that changes because an entity sits between the trustee and the money. The corporate form is not a fiduciary exemption. A trustee who controls the company his trust owns is exercising trust powers when he decides what that company pays him.
The remedies are substantial. A beneficiary may petition the probate court for instructions and to compel an accounting (§ 17200). The court may surcharge the trustee for losses caused by breach (§ 16440), remove him (§ 15642), and suspend his powers pending hearing where the circumstances warrant. Where property has been taken in bad faith, Probate Code § 859 provides for twice the value of the property recovered, plus attorney fees. Where the conduct constitutes financial abuse of an elder or dependent adult, attorney fees and costs are mandatory on a successful claim.
How a beneficiary reaches the company’s books
This is the practical question, and it has a practical answer.
The beneficiary is not a shareholder of the company. The trust is. Inspection rights over corporate books and records, and information rights in a limited liability company, belong to the entity’s shareholders or members — which means they belong to the trust, and the trustee is the one holding them.
That is not the obstacle it appears to be. A beneficiary can petition under § 17200 for an order compelling the trustee to account for entity-level transactions, to exercise the inspection rights the trust holds, or to produce what the trust has already received. Subpoenas and document demands aimed at the trustee in his fiduciary capacity can access the company’s records in court. When a trustee objects on the grounds that the beneficiaries should not be involved in the company’s affairs, they are typically confirming that they should be.
Forensic work differs from ordinary trust accounting work. It requires a professional who reads the company’s general ledger, payroll records, related-party disclosures, and compensation agreements—not just the trust’s schedules. That distinction decides these cases.
What to do first
- Obtain the trust instrument in full, including all amendments, and the provisions governing the trustee’s compensation and business powers.
- Obtain every trust accounting delivered to date, and identify precisely what the trust received from the company each year.
- Obtain the company’s governing documents — articles or certificate, bylaws or operating agreement, and every amendment — and read who holds authority, in what capacity, and how it can be removed.
- Identify any entity in which the trustee holds a personal interest that transacts with the company.
- Make a written demand for information before filing anything. The response, or the absence of one, becomes evidence.
- Preserve records. Send a litigation hold before the trustee knows a claim is coming.
Steps one through four are usually possible without a lawsuit, and they determine whether the case is worth bringing.
Can you afford to bring this case?
Most beneficiaries in this position assume they cannot. The trustee controls the company, the company generates the money, and the trustee will fund his defense from assets that should have been the beneficiary’s inheritance.
That asymmetry is real, and it’s why many of these cases are never brought.
.
Hackard Law represents beneficiaries in California trust and financial elder abuse litigation on a contingency basis. There is no hourly billing and no retainer. If there is no recovery, there is no fee. The firm advances the costs of investigation, forensic accounting, and expert work.
The firm works with a carefully selected network of co-counsel throughout California’s major counties, and focuses on significant cases. We welcome referrals from wealth advisors, certified public accountants, estate planning lawyers, and professional fiduciaries who encounter these facts but do not pursue legal action.
 Michael Hackard is the founder of Hackard Law, a California trust and estate litigation firm with more than five decades of experience protecting the inheritance rights of families across Sacramento, the San Francisco Bay Area, and Los Angeles. He is the author of six published books on inheritance protection and has produced more than 1,000 educational videos with over seven million views.